The Real Number
That Determines Whether Your Retirement Actually Works —
Or Just Looks
Like It
Works Until It Doesn't.
"A million-dollar nest egg under the conventional system delivers about $30,000 of actual spendable income per year. The same million, restructured, has historically delivered $120,000. Tax free. From the same starting balance"
ON SOUND
Calculate & Compare Your Retirement Income Number
-
See the real income your money can produce after taxes, markets, fees, and
withdrawals.
-
Compare the Conventional System vs. The Legacy Multiplier Strategy.
-
Discover how the same $1 million can deliver up to 4X more income.
Discover
Your Income Potential ➔
Reserve
My Strategy Session Today
It's Free. No Obligation. Takes Less Than 60 Seconds.
"There is a number you have probably never been told to calculate. Not your account balance. Not your projected return. Your real number — the one that determines whether your retirement actually works, or just looks like it works until it doesn't."
You've Probably Suspected This Already.
The financial industry has spent decades training you to watch one number. Your account balance.
Every quarter your statement arrives. You feel secure when it goes up. Afraid when it goes down. The industry profits from both reactions.
But here's the part nobody talks about:
That number isn't the number that determines how you live in retirement.
The number that determines your life in retirement is what you actually take home — every month, after taxes, after fees, after inflation — for the rest of your life.
That is your real number.
And the conventional system was never designed to maximize it.
After federal + state ordinary income tax. From a million dollars. After a lifetime of saving.
You've probably noticed something. The math doesn't quite add up when you run it forward honestly.
A 401(k) with a million-dollar balance. The standard 4% withdrawal. Forty thousand dollars a year — before the IRS takes its share. After federal and state income tax, most Americans are looking at $28,000–$32,000 of actual spendable income. From a million dollars. After a lifetime of saving.
That's the number nobody at your financial institution wanted to put on paper.
If you've ever quietly wondered whether the products you were sold were chosen because they served you — or because they served the institution that sold them to you — that suspicion was earned. It wasn't paranoia. It was pattern recognition.
There's a different number on the other side of that gap. And it's not produced by saving harder, taking more risk, or hoping the market cooperates.
It's produced by a completely different architecture.
One the banks have been using on their own balance sheets for centuries. One that was never illegal, never hidden, never complicated — just never shown to you, because the people positioned to show it to you were financially incentivized to show you something else.
What is it? And why does almost nobody talk about it?
That's what the film above uncovers.
There's a version of that gap with your numbers at the top. Your income. Your tax rate. Your deductions. Your actual monthly take-home — the number that determines how you live, not how your statement looks.
We built a calculator that shows it to you. Not as a projection. Not as an illustration. As simple arithmetic on your own numbers, run in real time.
Most people who run it are stunned — not because the math is complicated, but because nobody had ever been willing to put it on paper for them before.
Fifty Years. One Question.
A career spent inside the system — and the moment it failed the people who trusted it most.
In 1974, a 23-year-old named Steve Sousa walked into the ground-floor offices of Pacific Life in Newport Beach, California.
He'd been recruited by a man named Bill Palmer — whose son, Carson Palmer, would later become one of the most celebrated quarterbacks in professional football. But that's the thing about the financial industry. The names that matter most are rarely the ones that end up famous.
Steve came into the business looking for something specific. He wanted a career where his own work and creativity determined his income — not a boss, not a ceiling, not a salary review. He didn't know it yet, but he had just walked into a room with three of the most important financial producers of the next fifty years.
Guy Baker, who is still producing in his eighties today. Jim Benson. And Peter Mullen — already, at thirty, on his way to becoming the greatest insurance producer in the industry's history.
Steve was watching legends. He just didn't know it yet.
"I had clients with all of their retirement money in the market. And I had no answer for them."
Most advisors, faced with that kind of reckoning, find a way to rationalize continuing. Steve went looking for a better architecture instead.
For thirty years, Steve built his practice the way most successful advisors did. Variable universal life. Mutual funds inside a tax-advantaged structure. The 1980s cooperated. The 1990s cooperated harder. Double-digit returns. The Contra Fund. Growth Fund of America. An Asian fund that returned 105% in a single year.
Steve genuinely believed he had the best product in the marketplace.
Then 2000 happened. Then 2001. Then 2002.
Three consecutive years of losses. Then a four-year recovery — and then October 1st, 2007, when the S&P 500 began an 18-month, 65% collapse.
Steve had clients with all of their retirement money in the market. And he had no answer for them.
One of those clients was Dave Baker — the commissioner of the Arena Football League. A man who had done everything right. Saved carefully. Trusted his advisor. Planned ahead. And in 2008, at the moment he believed he was finally secure, the system delivered its verdict.
He had to go back to work.
Dave wasn't the only one. Steve had multiple clients in the same position. But Dave was the one Steve remembered most — because Dave had done everything the system said to do, and the system had still failed him.
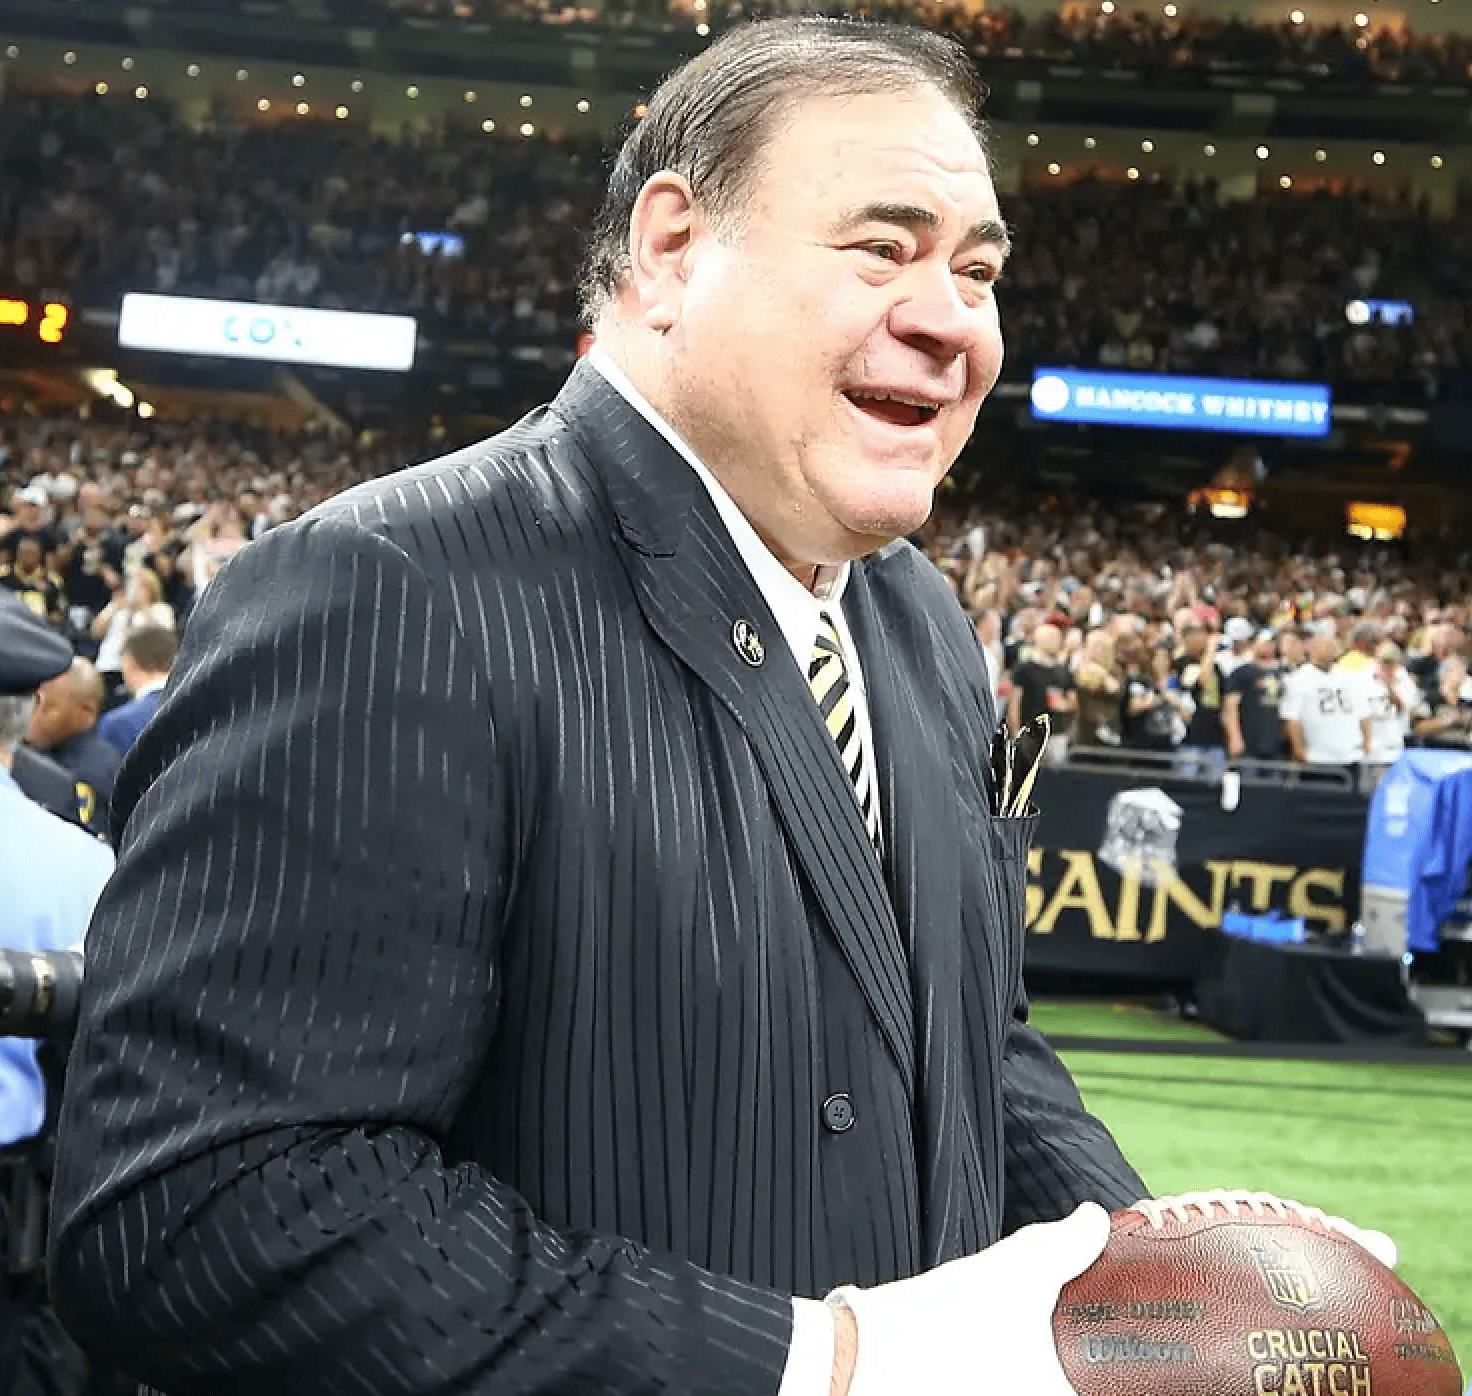
"Dave is the one I remember most — because he had done everything right. He had planned. He had saved. And the system still failed him."
Forced back to work after the 2008 crash. Later named President of the NFL Hall of Fame.
2008 was Steve's lowest production year since entering the industry. Not because the leads dried up. Because he stopped selling a product he no longer believed in for the purpose he'd been selling it for.
Most advisors, faced with that kind of reckoning, find a way to rationalize continuing. To tell themselves the market always comes back. That clients understood the risk.
Steve went looking for a better architecture instead.
That's not a small distinction. That's the whole story.
What he found — across the next several years, working alongside Bill Palmer and Jim Benson, sitting across from physicians at major hospitals running scenarios on a new product structure — was something he describes today as behaving unlike any instrument we've ever worked with.
Indexed Universal Life, designed not for the death benefit, but engineered specifically for tax-free retirement income. Built with a 0% floor — so a bad year cost a client nothing. Built with a participating loan structure — so the same dollar was working in two places at once. Built around a vehicle where the income came out as a loan, never as a taxable event.
That architecture, refined over fifteen years of real-client outcomes across crashes and recoveries, is what eventually became known as The Legacy Multiplier.
It wasn't a projection. It was a result.
"What I remember is the day I stopped checking my portfolio every morning. That background noise — the constant low-level anxiety about whether I was going to have enough — it just went quiet. For the first time in years, I wasn't carrying the weight of it."
If you're reading this, you already know what he means.
Three Traps Standing Between You And Your Real Number.
Each one investigated. Each one dismantled.
"It's not the product that makes the difference. It's how you design it. And that took a while to figure out."
"Isn't This Just Insurance? IUL Sounds Complicated — And Too Good To Be True."
When most people hear life insurance as a retirement strategy, one of two voices shows up in the back of their head.
Either: that's a death benefit, that's not a retirement plan.
Or: I've heard of IUL. It sounds complicated. If it were really this good, everyone would be doing it.
If you just thought either of those things, you're not alone. And you're not wrong to think it. Because that reaction is based on real experience with how most of these products are sold.
Most people have encountered IUL through an agent who sold it to maximize the death benefit — because that's where the commission was. What they ended up with was a policy that was over-insured, under-funded, and rigid.
That's not IUL failing. That's bad design.
And bad design is what the industry delivers most of the time. If you've encountered this and walked away skeptical — that skepticism was earned.
But here's what almost nobody has ever explained to you.
A life insurance contract is exactly what it says it is. A contract. Once signed, the laws in place at that moment govern it. If laws change tomorrow, those changes apply to new contracts — never existing ones. Your contract is locked. That isn't a technicality. That's how contract law has worked for centuries.
And inside a properly designed Indexed Universal Life policy, something happens that doesn't happen anywhere else in personal finance:
Your earnings are tied to the performance of indexes you already know — the S&P 500, the Dow, the NASDAQ.
But your cash value is never actually invested inside them.
It tracks the performance. It does not share the risk.
Read that twice.
When the index has a good year, you participate in that growth. When it has a bad year, your credited return is zero. Not negative. Zero.
You don't lose ground. You don't have a recovery problem. You just wait. And you already know the market comes back — you just removed the cost of waiting for it.
That's the first pillar of the Legacy Multiplier. Principal protection — not by stepping away from market growth, but by being tied to it without being trapped inside it.
And to anyone who says — if this is so good, why doesn't everyone do it? — the answer is the part of this nobody likes to say out loud:
Because the people positioned to show it to you are financially incentivized to show you something else.
"I'm Too Far Behind. And Leverage Is Dangerous."
Almost every person who understands principal protection arrives at the same next question.
That's great for what I already have. But is it enough? I'm behind. I haven't saved as much as I should have. Even with a floor, I don't see how I get to where I need to be.
If you've ever thought that, you're in the majority. Not the exception.
That fear is not a personal failure. It's a rational response to a system that capped your growth and then told you the cap was the best available option.
The only real answer is the one that makes most people uncomfortable the moment they hear it.
Leverage.
Stop for a second. Because we already know what just happened in your head.
The moment most people hear leverage, they think of 2008. And they should. Because the financial industry let people borrow against their homes at 100% of value. Zero down. The moment housing prices dropped, millions were underwater overnight.
Dave Ramsey built an entire career warning people about exactly that. For unsecured debt — credit cards, car loans on depreciating assets, personal loans with nothing backing them — he is absolutely right. Most people would agree with everything he says about that kind of debt.
But that's not the only kind of debt. And that distinction is exactly what the system never bothered to explain.
- — Nothing backing it
- — Drains net worth
- — Ramsey is right: avoid it
- — Asset earns the spread
- — Builds wealth on capital you don't own
- — How every bank in the world operates
The problem in 2008 wasn't leverage. It was uncontrolled leverage — no floor, no limit, no managed ratio between the loan and the asset underneath it. The moment the asset dipped, everything collapsed.
The banks learned from it. That's why they now require 20% down on a home purchase. They didn't stop using leverage after 2008. They managed it better.
And here's the question worth sitting with for a moment:
If that system is good enough for every bank in the world to organize itself around — why shouldn't it work for you?
Inside the policy, your principal is compounding inside a zero-floor structure. And alongside it, the policy is using borrowed capital — at a fixed loan rate — deployed against an indexed return that has historically averaged 8.8%, with a 14% cap and a 2% floor.
When the borrowed capital earns more than the loan costs — while your original principal is simultaneously earning its own return — the same dollar is working in two places at once.
That's what closes the gap. Not saving harder. Not taking on market risk. Not hoping. Using the same mechanics the institutions built for themselves — with two protections the banks themselves don't offer:
Principal can't collapse the way a housing market did in 2008.
The same dynamic boundary that protected the banks — applied to you in real time.
"Even after I understood the downside was protected, I still had this feeling that the growth wasn't fast enough. That by the time I needed the income, I wasn't going to have enough. Protection solved one problem. But I still had another one underneath it."
That's why Ryan Turner saw a 47% net return in his first year after making the switch.
He didn't do anything extraordinary. He made one decision — to stop accepting a ceiling that wasn't serving him — and let the design do the rest.
And if you're thinking that sounds like someone else's story, not mine — that's exactly what Ryan thought too.
"What If Tax Laws Change? What If Inflation Eats My Savings?"
The last fear is the quietest one.
It doesn't usually come up in the first conversation. It arrives at two in the morning, when the thinking gets honest.
What if tax rates go up? What if inflation keeps eroding what I've built? What if the laws change and something outside my control takes away what I worked for?
These are not irrational fears. They're the smartest questions in the room. And they deserve a real answer — not a reassurance.
This is the foundational principle of contract law that the ultra-wealthy have organized their entire financial lives around.
And it's available to anyone who signs one.
Most people, when they think about tax-free retirement income, think of the Roth IRA. And they're right to — it's a genuine step in the right direction. But the Roth has contribution limits. No principal protection. And it's entirely dependent on market performance.
The Roth is what Congress was willing to offer the individual. It is not what the banking system uses for itself.
The Legacy Multiplier is the system the banking sector built for itself — restructured and made accessible to you. Same mechanics. Same legal protections. Same tax advantages.
Your own private banking system. Working the way the institutions' systems work. For you. In retirement.
So Let's Walk Through What We Found.
That a 0% floor eliminates the down years that permanently damage traditional portfolios — and thirty years of index data says it is — then the foundation of this architecture is not just stable. It is structurally superior to any portfolio that exposes principal to unrecoverable losses.
That managed leverage allows the same dollar to earn in two places simultaneously — and Ryan Turner's 47% first year says it is — then the income potential is not an illustration. It is a real, repeatable, structural advantage.
That the external fears most people carry — rising taxes, inflation, law changes — each have a structural answer built into the design, then the fear that something outside your control will stop this from working isn't a reason to hesitate. It's a reason to make sure you're working with someone who has built those answers in.
If those three things are true — and we've walked through the evidence for each of them — then where does that leave you?
It leaves you with a choice most people never realize they have.
Not between a good retirement system and a mediocre one.
Between a system that was designed to sustain the institution — and a system that was designed to sustain you.
Is This For You?
- ✓Within 10–20 years of retirement — or already in it.
- ✓Carrying a quiet feeling that your number might not be enough.
- ✓Holding liquid, accessible investable assets.
- ✓In reasonably good health, able to qualify for life insurance.
- ✓Have sensed the financial system wasn't built with your retirement in mind.
- ✗Confident the conventional system is delivering everything you need.
- ✗Looking for a guaranteed-return shortcut that skips the design work.
- ✗Inclined to keep your eyes off the math.
- ✗Locked entirely inside a current 401(k) or pre-59½ IRA funds.
We'd rather be direct about that now than waste anyone's time on the call.
For the people who just read that list and recognized themselves — we built two things specifically for you.
Not for everyone who sees this page. For the people who watched the film, ran the math in their heads, and felt something shift. The people who are ready to stop wondering and find out.
This is what we put together.
What You Get — And What It's Worth.
Knowing about a strategy and having it working for you are two completely different things.
Most financial conversations start in the wrong place. An advisor asks about your goals and your risk tolerance — and then shows you what they already had planned to show you. Nothing in that process is built around your specific numbers.
This is different. When you reserve your Legacy Multiplier Strategy Session, our team sends you the Real Number Assessment — a focused intake questionnaire that gathers the specific data points your advisor needs to do the work before the call begins: your income, your tax situation, your current retirement architecture, and what you actually want retirement to look like.
Your advisor then spends a full week preparing. Gathering data. Building a picture of your situation. So the moment you get on the call, the conversation is already about you — not about a product category, not about a generic strategy, but about the specific gap between what your current plan is projected to produce and what may be possible inside a properly designed Legacy Multiplier structure.
Your Legacy Multiplier Strategy Session runs approximately 60 minutes in length. Your advisor will work through five specific areas with you:
- 01 →Your real number — the actual net spendable income your current strategy is projected to produce, after taxes, every month in retirement. Not the balance. The number you actually get to spend.
- 02 →Your tax exposure — how much of your retirement income may be silently lost to federal and state taxation before it ever reaches you, and what a tax-free structure would change about that picture.
- 03 →Your volatility risk — what market downturns could do to your future income under your current architecture, and whether a zero-floor design would change the math.
- 04 →Your principal protection — a clear assessment of whether the foundation your retirement is currently built on is structurally capable of surviving the kind of losses that ended Dave Baker's retirement on schedule.
- 05 →Your leverage opportunity — whether collateralized leverage could close the gap between where you are today and the income you actually want and need in retirement — and what that would look like in your specific situation.
The analysis and personalized strategy review you'll receive in this session — the kind that typically requires walking into a financial advisor's office and writing a check for more than twenty-five hundred dollars — is yours today at no cost, as a direct result of watching this documentary.
Available at no cost as a direct result of watching this film. Schedule your session and the Real Number Assessment intake arrives the same day.
FREE · NO OBLIGATION · REAL NUMBER ASSESSMENT INCLUDED
So after everything you've seen in this film, the question isn't whether the Legacy Multiplier works.
The question is — what would it mean for your retirement if it did?
If all of this did was give you a structure that removed market losses from the equation — so that a bad year cost you nothing instead of setting you back years — would knowing whether that structure fits your situation be worth approximately 60 minutes of your time?
And if all of it did was show you how to use the same leverage mechanics the banks have used for centuries — so that your money was compounding in two places at once instead of one — would that be worth a video Zoom call?
And if all of it did was show you how to generate retirement income that arrives tax free — without drawing down the principal producing it, so that you keep every dollar you receive — would that be worth finding out if it applies to you?
Most people answer yes to all three without hesitating.
If you leave the strategy session without a clearer, more honest picture of your retirement than you walked in with — we haven't done our job.
Nothing will be sold during this session. No obligation, no pressure, no commitment. This is an educational strategy conversation designed to help you determine whether the retirement architecture you're currently relying on is capable of producing the outcome you actually want. The only commitment we're asking for is approximately 60 minutes of your attention. Everything else is ours to earn.
Just say so, and we'll schedule a second conversation at no cost until we get it right.
Ryan Turner didn't describe his result in numbers and percentages.
He described it as quiet.
The background noise he'd been carrying for years — the constant low-level anxiety about whether he'd have enough, whether the things that mattered most to him were protected — it just stopped. There was a sense of peace. That's what the right structure does. And that's what we're offering you the chance to find out.
We reserve a limited number of strategy sessions each week — not as a marketing tactic, but because every case is reviewed individually before the Zoom call. Once those spots are filled, the calendar closes until the following week.
The people who benefited most weren't the ones who came in with the most money. They were the ones who started soonest.
Money can be recovered. Time cannot.
Schedule Your Session. We'll Do the Work Before You Arrive.
Find out how wide the gap really is — between what you think you have and what you'll actually get to keep. Because the longer that gap goes unaddressed, the harder and more expensive it becomes to close.
Schedule your Legacy Multiplier Strategy Session today. Your advisor spends the week before preparing. You arrive knowing your real number.
FREE · NO OBLIGATION · REAL NUMBER ASSESSMENT INCLUDED
"If you take nothing else from this page, take this: the worry you've been carrying — about whether you'll have enough, about whether the system you've been trusting is actually working — that worry doesn't go away on its own."
It only goes quiet when you finally see your real number on paper and know what to do about it. Most people will reach retirement without ever having calculated that number honestly. Not because they weren't paying attention. Because the system they were in was never incentivized to show it to them.
You don't have to be one of them. Reserve your Legacy Multiplier Strategy Session. Let us do the work. The clarity lasts the rest of your life.
Your advisor spends a week with your numbers before you ever get on the call. By the time you arrive, you're not starting from scratch — you're starting from the truth. It either confirms the worry, or quiets it permanently. Either way, you'll finally know.
The question isn't how much money you've accumulated. The question is how much of it you'll actually get to keep.
Not whether you should commit. Not whether you should change everything. Just whether a five-minute assessment and a strategy session of approximately 60 minutes are worth your time for the clarity they produce.
FREE · NO OBLIGATION · 3 SPOTS AVAILABLE THIS WEEK · REAL NUMBER ASSESSMENT INCLUDED